Nidec is preparing to walk away from the business it once billed as its ticket to the electric era. According to reports, the Japanese components giant is seeking to divest its automotive electric motor unit, a division built squarely around supplying Stellantis. The timing tells its own story. When a supplier of Nidec’s scale decides that traction motors for EVs are no longer worth the capital, it says less about Nidec’s engineering than about the demand it was counting on.
What Nidec is putting on the block
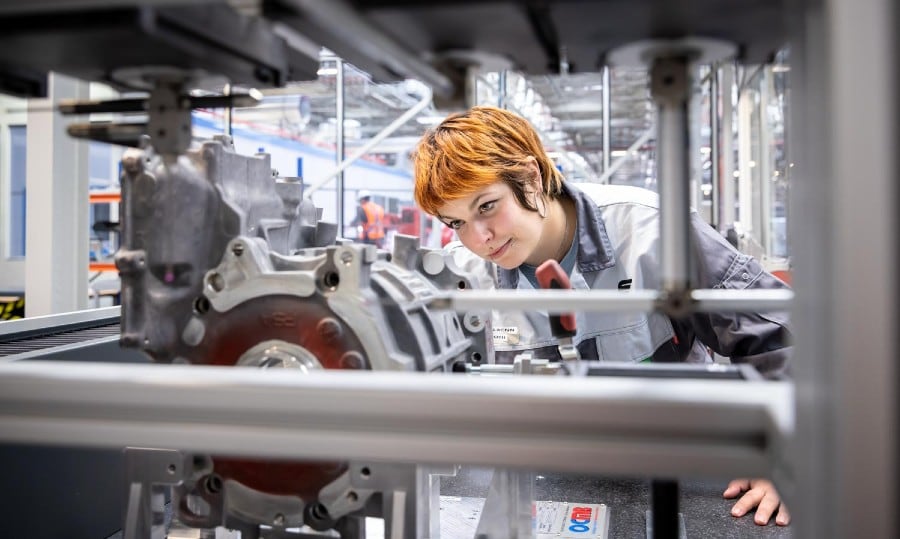
The division in question makes traction motors, the units that turn electrical energy into motion at the wheels of a battery electric vehicle. Nidec spent years and considerable investment building an automotive arm to serve the coming wave of electrification. Executives framed it as a growth engine, one that would ride the shift away from combustion engines and into a new industrial era.
That pitch has run into the less glamorous reality of making money in automotive supply. Traction motor manufacturing is capital intensive, margins are thin, and volumes only work if carmakers actually build the cars those motors were designed for. Nidec’s automotive business has struggled on profitability, and its fortunes have been tied to a narrow set of customers. When those customers change their minds, the arithmetic collapses quickly.
The Stellantis problem
The Stellantis connection is the crux of it. Nidec’s automotive motor operation has been closely linked to the Franco-Italian-American giant, and Stellantis has spent the past year steadily revising its electrification plans downwards, according to reports. Production schedules have been pushed back, model launches rephased, and investment reallocated. For a supplier that tooled up to meet those original volumes, the result is painful: capacity without demand, and fixed costs spread across fewer units.
This is not a Stellantis-only phenomenon, but Stellantis has been one of the most vocal in pulling back. The company has delayed several electric models, adjusted its battery strategy and warned that the pace of EV adoption in Europe and North America is not matching the regulatory timetables that were drawn up only a few years ago. Suppliers read those signals in their order books long before the headlines arrive.
The wider policy backdrop has shifted too. In the United States, regulators have moved to soften the trajectory manufacturers were previously working towards, replacing the far more aggressive Biden-era framework with rules that allow a longer runway for combustion and hybrid models. Suppliers who invested on the assumption of a hard deadline are left holding tooling for a market that is arriving more slowly.
Why this ripples through the supply chain
Nidec’s move is best understood as one entry in a longer list. Across the automotive supply base, companies that expanded aggressively for an electric future are now consolidating, delaying capacity, writing down assets or exiting segments entirely. Motor and inverter specialists, battery component makers and semiconductor suppliers have all announced retrenchments or strategic reviews over the past 18 months.
The pattern is consistent. Carmakers announce ambitious EV targets, suppliers invest against those targets, and then the targets move. Because automotive tooling and factory commitments run on multi-year cycles, suppliers cannot simply switch off capacity when a customer changes its mind. They absorb the cost, or they sell the business.
There is a second-order effect that matters just as much. When a major supplier exits a segment, the remaining players gain leverage, and carmakers lose redundancy in their supply base. That is fine while volumes are soft. It becomes a problem if demand recovers faster than expected, because rebuilding a divested motor business takes years, not quarters.
It is worth remembering that the underlying technology has not stood still while the business case wobbles. Motor and inverter efficiency continues to improve, and the engineering ambition behind electric drivetrains is not in question. The commercial confidence is.
What happens next
The obvious question is who buys a traction motor business in a soft market. Potential buyers fall into a few categories: larger tier-one suppliers looking to consolidate capacity at a depressed valuation, private equity firms betting on a medium-term recovery, or industrial buyers, particularly in Asia, seeking technology and customer access. Chinese and Korean suppliers with strong domestic EV demand may see strategic value where Western buyers see risk.
For Stellantis, the immediate impact is manageable but not trivial. The company has been diversifying its electric motor sourcing, and losing a supplier relationship of this kind is unlikely to halt any current programme outright. The bigger issue is what it signals to the rest of its supply base. Suppliers watching a major peer exit will price future Stellantis contracts with more caution, demanding firmer volume commitments or higher unit prices to compensate for the risk.
Whether other suppliers follow depends largely on how quickly the demand picture stabilises. If European EV registrations continue to grow modestly and the US regulatory environment stays permissive, more suppliers will conclude that the segment is not worth the wait. If adoption accelerates again, the companies that stayed in will be well positioned, and the ones that left will be explaining the decision to their boards.
Nidec’s retreat from automotive electric motors is a small headline with a large implication. The electric transition is not reversing, but it is being rescheduled, and the cost of that rescheduling is landing on suppliers who invested against timetables they did not control. Stellantis’s pullback did not create this problem on its own, but it crystallised it.
The companies that emerge strongest from this period will be those that treated electrification as a variable rather than a certainty, keeping enough flexibility in their industrial footprint to survive a slower ramp. Nidec has chosen to buy that flexibility by selling the business. Others will be weighing the same calculation, and the answers they reach over the next year will shape who supplies the motors for the cars that eventually do get built.